Maria Alvarez did not leave the bank with forty-eight thousand dollars in cash.
The check still required processing.
A portion remained subject to a standard hold while the settlement account cleared.
That was legal.
Reasonable.
And completely different from treating Maria as if the amount itself proved dishonesty.
The wage case began four years earlier at the Harbor Crown Hotel.
The hotel owned the building and brand.
Guest-room cleaning, laundry, banquet setup, and some kitchen work were supplied through an outside staffing contractor called Premier Hospitality Services.
Maria worked under Premier.
Guests assumed the housekeepers were hotel employees.
Their uniforms carried the Harbor Crown name.
Their paychecks did not.
Premier’s payroll system included several practices workers found difficult to understand.
Automatic meal deductions appeared even when a housekeeper worked through the break.
Banquet service charges appeared on customer bills but reached staff inconsistently.
Workers purchased required uniforms through paycheck deductions that sometimes continued after the full cost had been collected.
When rooms were assigned before shift start, preparation time went unpaid.
Overtime hours were occasionally split across related payroll companies.
One missing amount looked small.
Seven years of small amounts became significant.
Maria noticed first because her daughter helped her compare pay stubs.
Maria cleaned between fourteen and eighteen rooms per shift.
She knew exactly how many hours she spent inside the hotel.
The pay stubs described fewer.
She asked her supervisor.
He said the software rounded time.
She asked why uniform charges remained.
He said replacement costs.
She had received no replacement.
Other workers had similar questions.
A laundry worker named Rosa Bell kept photographs of every time clock.
A banquet server saved customer receipts showing service charges.
A maintenance employee kept schedule texts proving employees reported before paid time began.
They contacted a worker center.
The center helped them file wage claims.
Premier denied intentional wrongdoing.
The company argued that payroll errors, subcontractor confusion, authorized deductions, and differing work classifications explained most discrepancies.
The case lasted years.
Some workers left the state.
Some accepted individual settlements.
Others remained.
The final agreement did not declare every allegation proven.
It created a common fund to repay calculated unpaid wages, deductions, statutory amounts, and fees.
Maria’s payment was high because she had worked for many years and because several categories applied to her.
It did not make her wealthy.
After taxes, legal allocations, and debts accumulated during the case, the money would repair part of a long loss.
The court appointed an independent administrator to calculate and distribute checks.
The administrator chose Harbor Trust as the issuing bank because it had branches near many workers.
Harbor Trust’s central compliance department sent verification instructions to local branches one day before distribution.
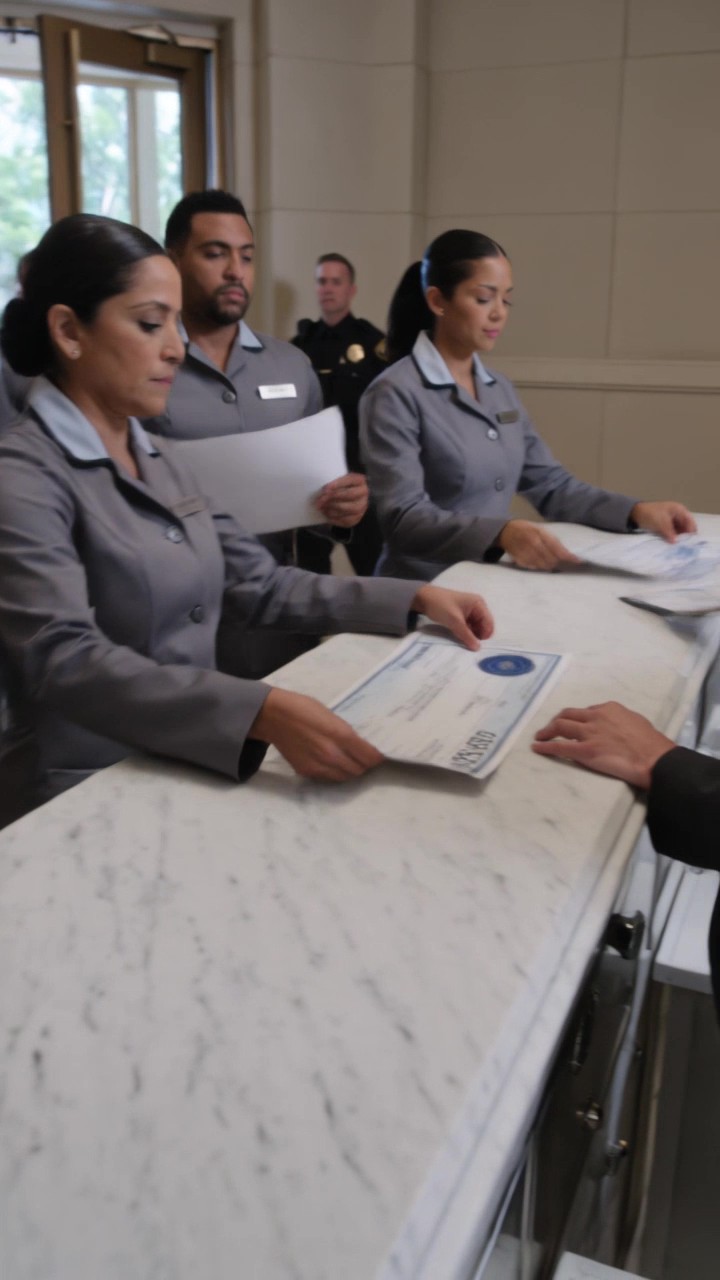
The email identified the account, check design, blue seal, administrator phone number, and expected range of amounts.
Celeste Hart received the email.
She skimmed the subject line.
Then forwarded it to the operations inbox without reading the attachment.
The branch opened the next morning with a long line.
Maria arrived first.
The teller’s screen generated a large-deposit alert.
That alert did not mean fraud.
It required identity verification, check inspection, issuer confirmation, and a hold decision.
Celeste turned a neutral process into a judgment.
She compared the check with Maria’s current balance.
Asked whether housekeepers could earn enough to be owed that amount.
Questioned the hotel key card.
And instructed security to stand near Maria before the issuer had been contacted.
At the review, Celeste said she was protecting the customer.
“If the check were false, Ms. Alvarez could lose access to her account.”
That was partly true.
Depositing fraudulent funds can harm customers.
The bank had a duty to verify.
The investigator asked:
“Why did you not use the central verification notice?”
Celeste answered:
“I had not read it.”
“Why did you not call the court administrator through the number in the bank directory?”
“The lobby was busy.”
“Why did you move the customer to a security room before either step?”
Celeste had no procedural answer.
Her explanation had formed around Maria.
Small account.
Work uniform.
Accent.
Unexpected amount.
The bank’s system asked:
Is the check unusual?
Celeste answered a different question:
Is this amount believable for a person like her?
The eleven workers who entered were not staging a surprise attack.
They had agreed to meet outside because several felt nervous depositing large checks.
The settlement administrator attended after learning one worker had been turned away at another institution the previous year.
When Maria texted that security was waiting, the group entered together.
Their matching checks made the error visible.
The official verification letter made it undeniable.
Harbor Trust deposited every valid check.
The workers received written hold schedules.
Some funds became available within days.
Larger portions cleared after issuer confirmation.
Nobody was handed a suitcase of money.
Nobody needed a dramatic exception.
They needed the ordinary system to work without humiliation.
Maria filed a complaint.
At first, the bank offered to waive future account fees and provide a private apology.
She refused.
“The security guard stood beside me where everyone could see.”
The correction also needed to be visible.
Harbor Trust issued a public statement acknowledging that staff failed to follow established settlement-verification procedures and treated a customer’s occupation and account history as reasons for suspicion beyond the required review.
The bank did not publish Maria’s balance or immigration history.
Accountability did not require exposing more of her private life.
Celeste was removed from branch management during investigation.
She later returned to the bank in a non-supervisory operations role after discipline and retraining.
Some workers believed she should have been fired.
Maria did not decide the punishment.
She asked the bank to change what the next worker would face.
Large checks could still be reviewed.
Security could still respond to actual threats.
But tellers had to explain the verification steps before moving a customer.
Occupation, clothing, accent, and current balance could not substitute for document checks.
If a customer supplied a court or government notice, staff verified through an independent official directory rather than dismissing the paper.
Interpreter access became available without requiring the customer to bring a family member.
And security interviews required a documented reason beyond “unusual amount.”
The bank also created group deposit appointments for court settlements, disaster payments, and community distributions.
Not separate entrances.
Not special rooms hidden from other customers.
Scheduled staff who understood the source.
The settlement administrator changed her process too.
Future recipients received a plain-language sheet explaining holds, taxes, fraud precautions, and what a bank could reasonably ask.
Workers were warned not to pay anyone who promised instant access to settlement funds.
Respect and caution could exist together.
Maria used the cleared money slowly.
She paid credit-card balances accumulated while her wages were missing.
Replaced a car that failed inspection twice.
Created an emergency fund.
Paid for part of her daughter’s respiratory-therapy program.
She did not quit housekeeping immediately.
The settlement compensated past work.
It did not create a pension.
Maria stayed at Harbor Crown for another year while applying to become a hotel training coordinator.
The hotel had ended its contract with Premier and brought many positions in-house under a monitored labor agreement.
Maria accepted the coordinator job because new housekeepers kept asking the same questions she once asked:
When does paid time begin?
Where do service charges go?
What can be deducted?
She built those answers into orientation.
The hotel resisted putting the wage case in training materials.
Maria insisted.
“People should know why the rule is written.”
The settlement did not prove every manager had stolen.
It proved systems can make theft look like rounding, confusion, and small deductions no single worker has time to challenge.
At Harbor Trust, a photograph of the eleven blue-sealed checks was used in training.
The workers’ names and amounts were removed.
The caption read:
UNUSUAL DOES NOT MEAN IMPOSSIBLE. VERIFY THE INSTRUMENT. DO NOT INVENT THE CUSTOMER.
One year after the incident, Maria entered the same branch in ordinary clothes to deposit her coordinator paycheck.
A new teller asked for identification.
Reviewed the check.
Explained that part of the deposit would be available immediately.
No one recognized her.
That was fine.
Fair treatment should not depend on remembering the famous complaint.
Near the door, Maria saw a hotel dishwasher holding another settlement check.
He looked nervous.
She did not speak for him.
She waited nearby.
The teller read the blue seal, opened the verification directory, and explained the hold.
The dishwasher nodded.
The transaction continued.
No crowd entered.
No security officer moved closer.
Maria left before he did.
The bank had once looked at forty-eight thousand dollars and decided it was too much to belong to a housekeeper.
The truth was the opposite.
It was only a fraction of what years of work had already taken from her.
Leave a Reply