The $96,000 remained in Charles Whitmore’s account.
The courier was detained until police arrived.
The person on the phone disconnected.
The shell company’s receiving account was flagged before any funds moved.
That was the practical rescue.
The emotional aftermath was less clean.
Charles sat in a private office with his granddaughter Maya.
He looked embarrassed.
Then angry.
Then embarrassed that anger had arrived before relief.
Fraud often works by making the victim believe speed proves love.
Stopping the payment can feel like stopping the rescue of someone they care about.
Charles had received the first call that morning.
A young woman was crying.
She said:
“Grandpa, please don’t tell Mom.”
The voice sounded distorted.
She claimed she had caused a traffic accident while using a friend’s car.
Then a man identifying himself as an attorney took the phone.
He said Maya faced immediate detention unless a confidential legal reserve was posted before noon.
He warned Charles not to contact family because the court had issued a temporary confidentiality instruction and because publicity could harm Maya’s future.
The story contained enough familiar pieces.
Maya had recently borrowed a coworker’s car after hers failed.
She had applied to nursing school.
She worried constantly about anything affecting background checks.
Charles knew those facts.
He did not know the scammers had obtained them through public posts, a compromised email account, and ordinary online searches.
The caller kept Charles on the phone while directing him from his home bank to a second credit union branch.
He was told his usual bank might delay the wire and “cause the judge to revoke the arrangement.”
The courier met him near the credit union entrance with printed instructions and a professional-looking badge.
Charles believed the man worked for the attorney.
He never asked why a court representative needed to stand beside him during a private transfer.
Panic reduced every question to time.
Nora Bell recognized the pattern because elder financial exploitation had become her work.
Eight years earlier, she had been a teller under Charles at Harbor Community Bank.
The bank was expanding aggressively.
Employees received targets for new accounts, insurance products, credit cards, and overdraft services.
Nora performed well at ordinary customer service.
She struggled with sales targets because she refused to describe optional products as required.
A regional manager began encouraging staff to prepare applications in advance for “eligible customers” and complete signatures during later visits.
Several older customers found accounts they did not remember requesting.
Nora reported the practice to Charles.
He agreed privately that the pressure had become unsafe.
Then the regional manager announced an internal audit.
Some questionable applications carried Nora’s employee code.
She had opened customer profiles during routine transactions.
Another employee later added products under the same session.
Charles faced a choice.
He could tell auditors the branch had used shared workstations and manager-approved shortcuts.
That admission could expose him to discipline.
Or he could describe Nora as a teller who resisted supervision, mishandled sessions, and created inaccurate applications.
Charles chose the second version.
He did not forge the documents.
He signed the termination recommendation.
The reason stated:
Unauthorized customer-product activity and failure to follow sales controls.
Nora protested.
She supplied emails warning about the shortcuts.
The bank said the messages showed disagreement with management, not proof she lacked involvement.
She was fired.
No criminal charge followed.
The employment record made future banking jobs difficult.
Nora found part-time work at a nonprofit tax clinic.
Then trained in consumer protection and elder-fraud prevention.
Years later, regulators investigated Harbor Community Bank’s sales practices.
The bank paid penalties and corrected customer accounts.
Charles had already retired.
Nora’s individual record was not automatically restored.
She requested review.
The bank responded that personnel files older than seven years were archived and the original decision could not be fully reassessed.
Charles never contacted her.
He told himself the regulatory case involved system-wide issues, not the specific applications linked to Nora.
That distinction protected him from remembering what he had done.
At the credit union, Nora saw him from across the lobby.
She recognized the courier’s badge first.
The seal used a county name that did not match the printed wire jurisdiction.
Then she heard the words confidentiality order.
Legitimate legal proceedings can involve privacy.
They do not prevent a person from independently verifying whether a family member is safe.
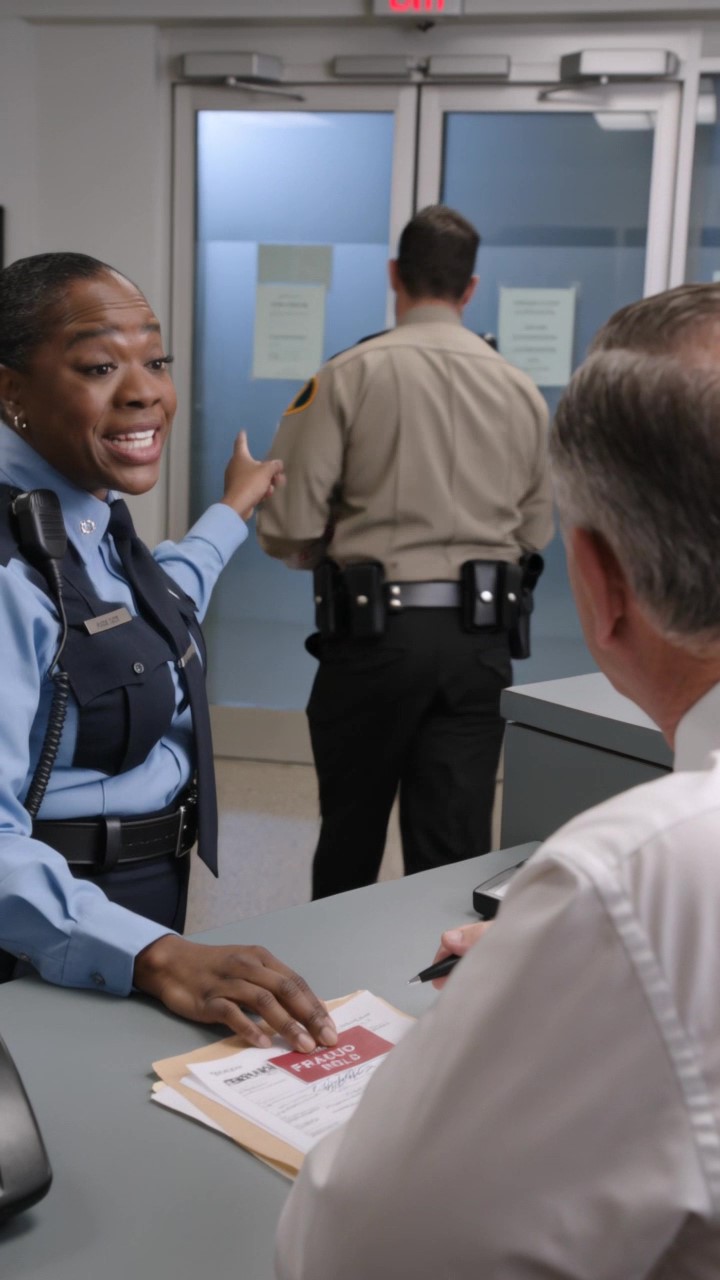
Nora approached the branch manager.
She did not seize Charles’s account or pretend to have authority over his money.
She identified herself as a county fraud counselor and asked for a temporary hold under the credit union’s suspected-exploitation policy.
The manager hesitated.
Charles was oriented.
He knew the amount.
He answered account questions.
Adults generally have the right to make poor financial decisions with their own money.
A bank cannot block every unusual transfer merely because family disapproves.
Nora pointed to specific indicators.
The new shell company.
The urgency.
The courier monitoring the transaction.
The instruction not to contact relatives.
The wire sheet containing inconsistent court information.
The manager authorized a short delay for independent verification.
Charles interpreted the delay through old history.
Nora had once challenged his management.
Now she stood over his retirement transfer.
He believed she was humiliating him publicly.
“You were fired for interfering with customers,” he said.
The statement was both an attack and a reminder of the record he controlled.
Nora continued anyway.
She asked staff to use the verified emergency-contact number attached to Charles’s account.
The first call reached Maya’s voicemail.
A second call reached the grocery store where she worked.
A manager sent her to the phone.
Maya said she was safe.
The credit union asked her to come because Charles remained unconvinced.
Scam victims sometimes believe the “real” family member on another line is part of law-enforcement secrecy or that the emergency has changed.
Maya arrived in uniform.
Her physical presence broke the story.
The courier attempted to leave.
Security detained him for police based on suspected fraudulent identification and his involvement in the transaction.
The wider investigation found he was a low-level participant hired to guide victims and collect confirmation that wires had been sent.
He did not control the network.
Police advised the family that recovering funds after an international wire would have been unlikely.
Charles had come within one signature of losing money intended for housing, medical care, and support for Maya’s education.
At first, he thanked Nora.
Then he said:
“I would have realized before it sent.”
Nora did not argue.
Maya did.
“No, you wouldn’t.”
Charles looked wounded.
Maya softened her voice.
“That is not because you are stupid. They kept you scared and busy.”
The distinction mattered.
Financial scams do not succeed only against careless or unintelligent people.
They exploit urgency, love, secrecy, authority, and shame.
Charles had managed a bank.
That experience made him more confident he could identify fraud.
It also made him less willing to admit uncertainty once the process began.
The credit union filed the required suspicious-activity reports and offered account protections.
Charles changed passwords.
Froze credit files.
Added a trusted-contact protocol that allowed the bank to notify Maya if future transactions showed exploitation indicators without giving her control of the account.
He remained the owner of his money.
Protection did not become family takeover.
The branch held a review.
The manager’s initial instinct had been to honor the customer’s stated instruction.
That principle remained important.
The review clarified that autonomy and verification could coexist.
A short hold required documented red flags, supervisory approval, and an immediate independent check.
Couriers or companions could not remain beside customers during private wire questioning.
Staff used contact information already on file, not numbers supplied by the person directing payment.
And the customer received a clear explanation of what the bank was doing and how long the pause would last.
Nora’s intervention could have ended there.
She saved the wire.
Charles went home.
The past remained.
Maya refused that ending.
She found the old regulatory settlement online.
Then asked Charles why Nora had said he used her name to save his job.
Charles told her the branch story.
His first version emphasized shared workstations and pressure from regional leadership.
Maya asked:
“Did you believe she opened those products?”
Charles did not answer.
“Did you sign the termination?”
“Yes.”
“Did she warn you before the audit?”
“Yes.”
“Then what part are you unsure about?”
Charles looked at his granddaughter.
The scam had placed him inside the experience of being judged through a story someone else controlled.
That did not make the situations identical.
It made avoidance harder.
He contacted Nora through the county office.
She agreed to one meeting with a consumer-law advocate present.
Charles brought copies of the old emails from a storage box.
He had kept them.
That fact angered Nora more than if he had lost them.
“You had the warnings.”
“Yes.”
“You knew the employee codes could remain open on shared terminals.”
“Yes.”
“You knew the regional manager wanted one person identified before the audit.”
Charles looked down.
“Yes.”
“Why me?”
“You were already challenging the program.”
“That made me less believable?”
“It made you easier to describe as insubordinate.”
Nora sat back.
The sentence was ugly.
Accurate.
Charles offered to contact the old bank.
Nora said:
“You are not asking them for a favor. You are correcting the statement you signed.”
He did.
Harbor Community Bank had changed ownership.
Its successor institution reopened the archived personnel review using Charles’s sworn statement, Nora’s emails, regulatory findings, and session records.
The bank could not reconstruct every application.
It removed the misconduct finding from Nora’s employment record and issued a neutral-to-corrective reference:
Nora Bell raised concerns regarding sales-control practices later included in regulatory review. Available evidence did not establish that she knowingly created unauthorized customer products.
The correction arrived eight years late.
It did not return lost wages automatically.
Nora pursued a negotiated settlement for part of the documented career harm.
The bank agreed without admitting every allegation.
Charles contributed no private payment.
Nora did not want money from him exchanged for forgiveness.
She wanted his evidence placed where his accusation had been.
He also issued a written statement to former branch employees.
He admitted signing Nora’s termination recommendation despite knowing management practices and shared sessions made the conclusion unreliable.
Some former coworkers forgave him.
Others did not.
Nora read the statement once.
Then filed it.
She did not return to banking.
Her fraud-prevention career had become meaningful.
She led workshops in senior centers, credit unions, churches, and housing communities.
Charles attended one workshop without sitting in the front.
Nora used a red fraud hold card as a teaching tool.
She explained:
A pause is not an accusation.
A customer remains the decision-maker after independent facts are checked.
Never trust the contact information supplied inside the emergency story.
Create family verification plans before fear begins.
At the end, Charles raised his hand.
“What if the customer becomes angry?”
Nora looked at him.
“They may.”
“Then how do you know when to stop insisting?”
“You document the red flags, verify quickly, explain the limit of your authority, and do not confuse their anger with proof you were wrong to ask.”
Charles nodded.
He had once used anger and hierarchy to end her questions.
Now a question had saved him.
Their relationship did not become friendship.
Maya remained in contact with Nora through the county program.
She invited her to speak at nursing-school orientation about financial exploitation affecting patients and families.
Charles helped fund no event.
No plaque carried his name.
The repair stayed proportional.
One year later, Charles received another suspicious call.
This caller claimed to represent the tax agency and demanded payment through a digital kiosk.
Charles hung up.
Then called the verified public number himself.
No payment was due.
He texted Maya:
I checked before I worried alone.
She answered:
Good.
Then added:
Call me anyway.
Charles did.
The $96,000 stayed in his retirement account.
He later used part of it for legitimate home-care planning and contributed to Maya’s tuition under a written gift arrangement that did not give him control over her choices.
Nora had saved the financial future of the man who damaged hers.
She did not do it because he deserved a clean ending.
She did it because fraud was happening in front of her and because refusing to act would have allowed his old betrayal to decide her present character.
Then she required the second rescue.
Not of his money.
Of the truth he had buried to protect himself.
Leave a Reply