Nina Alvarez was not asking the bank for charity.
She was asking it to find money it had already accepted.
That difference shaped the entire case.
Nina and her husband, Mateo, bought their small house twenty-one years earlier. It had two bedrooms, a narrow porch, and a leaking kitchen window they repaired three times before replacing. The mortgage was modest by current standards, but it had never felt easy.
Mateo handled most banking. He distrusted automatic withdrawals after an old payroll mistake and preferred in-person deposits or mailed money orders. Nina teased him about the green passbook, but she kept it after he died because it carried his handwriting in the margins.
When Mateo became ill, Nina took extra shifts in the hospital laundry. After he died, she continued making mortgage payments through money orders. She wrote the loan number carefully from the payment coupon. In January, February, and March, the bank stamped the money orders as received.
Then the servicing system changed.
The bank converted older loan files into a new platform. Most transfers worked. Some accounts with legacy numbers required manual confirmation. Nina’s loan number ended in a digit that appeared faintly on older coupons. During conversion, that final digit dropped from the system link used at the branch.
When Nina mailed or brought money orders, staff entered the visible number. The system did not reject the money. It placed the deposits into a suspense account for unmatched mortgage funds.
A suspense account is not automatically wrongdoing. Banks use it when money arrives without enough information to post correctly. The problem was what happened afterward.
No one contacted Nina by mail.
Automated notices went to an email address created by a loan officer during a refinance discussion years earlier. Nina had never used it. Paper notices were marked “electronic delivery active” because the old system had been migrated incorrectly.
By April, the mortgage platform showed three missed payments.
The loss-mitigation department sent digital warnings.
Nina did not see them.
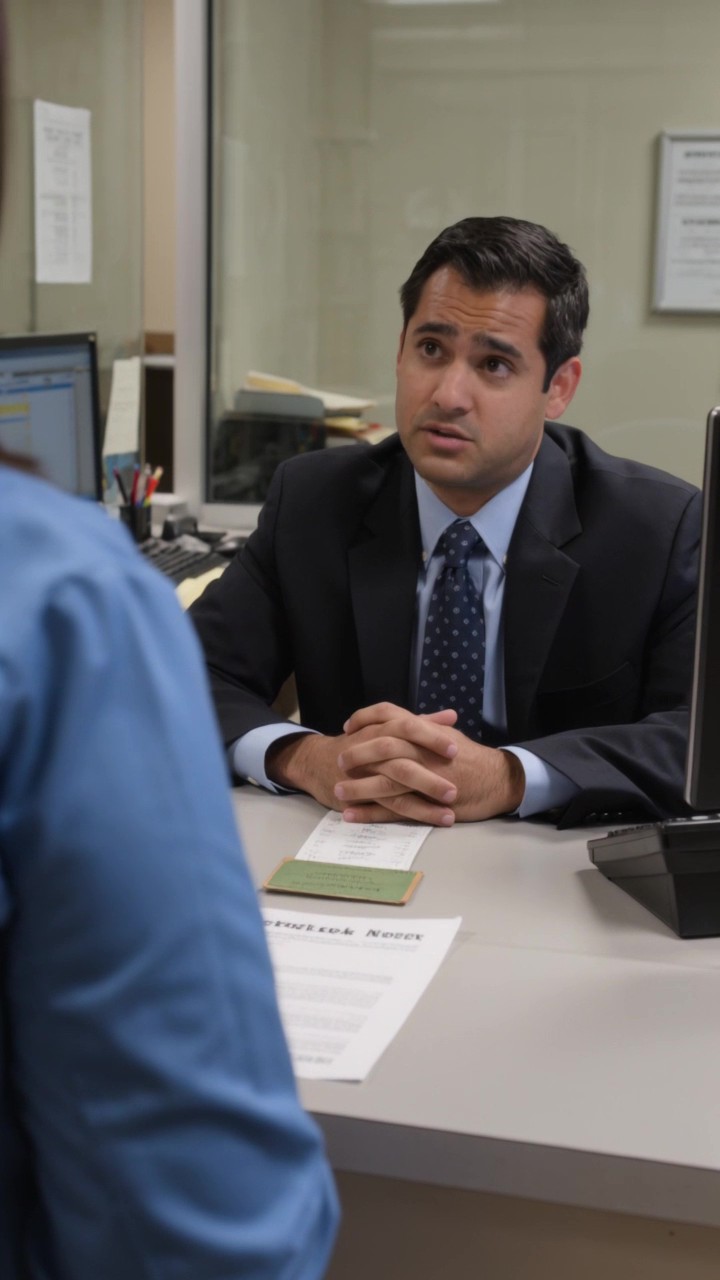
When a certified foreclosure notice arrived by mail, she took a day off work and came to the branch in uniform because she had no time to change.
Charles Whitmore saw a low-income customer with an old passbook, paper receipts, and little knowledge of digital servicing terms. He did not see a borrower with evidence.
He told himself he was being efficient.
The auction was already scheduled.
The modification period had passed.
The branch could not solve servicing problems.
All of that sounded procedural.
But procedures were not meant to replace checking the bank’s own stamps.
The retired teller, Evelyn Bell, had come to the branch to close a certificate of deposit. She recognized the green passbook design because she had worked during the era when the bank used that series. She also recognized the red transfer codes on the stamped receipts. They were not random. They identified internal batches used when branch deposits moved into suspense review.
Evelyn asked the assistant manager to search by batch number, not by loan number.
The three payments appeared.
The total covered January, February, and March, plus a small overage Nina had included to cover late fees she feared might exist.
The assistant manager escalated to the mortgage-servicing department while Nina remained at the branch. At first, the department said foreclosure activity could not pause without a formal research ticket.
Evelyn asked one question:
“Are you planning to sell a home tomorrow while holding the payments in your own suspense account?”
That question moved faster than a ticket.
The bank issued an emergency sale hold that afternoon. The auction was postponed, then canceled after reconciliation confirmed the funds belonged to Nina’s mortgage.
The three payments were posted effective the original receipt dates. Late fees, property inspection charges, and foreclosure legal fees were reversed. The bank also corrected the electronic-delivery error and restored mailed notices unless Nina personally changed the preference.
Nina still had work to do.
Her household income had dropped after Mateo died. Future payments remained difficult. The bank connected her with a legitimate loss-mitigation review, this time in writing and by phone. A housing counselor attended the call with her.
She received a temporary repayment adjustment based on current income, not a miracle cancellation. She kept the house, but the budget stayed tight.
Charles faced an internal review.
He argued that branch managers cannot manually halt every foreclosure based on old paperwork. The review agreed that not every paper claim is valid. It also found he dismissed multiple bank-stamped receipts, failed to search suspense batches, mocked legacy records, and relied on digital notices without verifying whether the customer had access.
His words mattered too.
A museum piece.
Digital notices.
Someone like her should have answered.
He did not say the last sentence aloud, but staff described the tone. Bias often appears in what a manager decides is not worth checking.
Charles lost authority over foreclosure-related branch decisions and was required to retrain. He remained employed in business accounts after discipline. Nina did not ask to decide his career.
She asked for a written correction.
The bank issued one:
Ms. Nina Alvarez made the January, February, and March payments on time. The payments were received by the bank and incorrectly held in suspense due to a servicing conversion error. Foreclosure activity was initiated in error and has been canceled.
Nina made ten copies.
One went in her kitchen drawer.
One to the housing counselor.
One to her daughter.
One stayed inside Mateo’s passbook.
The bank changed procedures.
Any foreclosure inquiry involving stamped receipts required a suspense-account search before staff could deny payment.
Legacy passbooks and old coupons were not proof by themselves, but they had to be treated as evidence to be researched.
Electronic-only notices for converted loans required re-verification.
Branch staff received training on money-order customers, limited internet access, and paper documentation.
And auctions could be paused when bank-held funds plausibly matched the account.
Evelyn Bell refused public praise.
“I was not a hero,” she said. “I knew where to look.”
Nina answered:
“That is exactly what I needed.”
Several weeks later, Nina returned to the branch to make another payment. She wore the same laundry uniform. A different manager invited her to sit.
She placed the money order and green passbook on the desk.
“I know the passbook is old,” she said.
The manager answered:
“Old records are still records.”
Nina did not smile immediately.
Trust takes longer than a corrected account.
At home, she placed the foreclosure notice behind the passbook, not to scare herself, but to remember what almost happened when a bank confused modern with accurate and old with worthless.
Mateo’s handwriting remained in the margins.
Nina added one note of her own:
They found the money.
Then, below it:
Make them look.
Leave a Reply