5 Money Habits Every First-Time Earner Should Build From Day One
There is nothing quite like the feeling of receiving your first paycheck or stipend. That number landing in your bank account feels like proof that all your effort finally paid off, and it comes with an intoxicating sense of freedom. But that same freedom can quickly turn into a trap. I still remember my early days at work, when a “quick” morning coffee with colleagues turned into a daily ritual, followed by an afternoon bubble tea run that somehow became non-negotiable. Before I knew it, my wallet was empty days before the next payday, and I had nothing to show for it except a stack of empty cups.
That experience taught me something important: the habits you build in your first few years of earning money shape your entire relationship with finances for decades to come. Get it right early, and money becomes a tool that gives you options. Get it wrong, and you spend years feeling controlled by every paycheck. The good news is that building healthy financial habits doesn’t require a finance degree — just a few practical, consistent choices. Here are five tips that helped me turn things around.
1. Apply the “Golden Rule” of 50/30/20
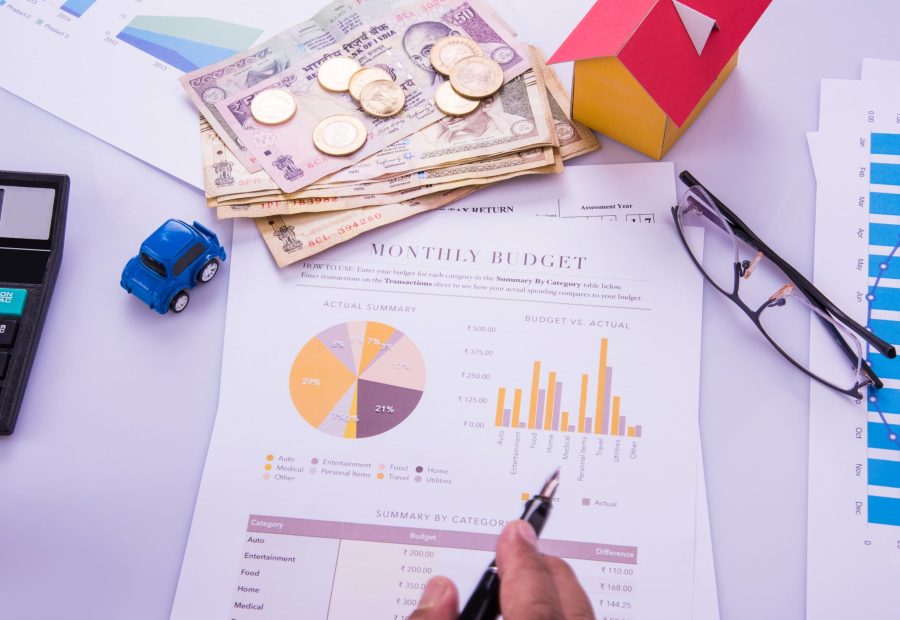
This is one of the simplest and most effective budgeting frameworks out there, and it’s a great starting point if you’ve never tracked your money before. The idea is to split your after-tax income into three buckets:
- 50% for needs — rent, groceries, utilities, transportation, and other essentials you can’t avoid.
- 30% for wants — shopping, entertainment, dining out, hobbies, and the things that make life enjoyable.
- 20% for savings or debt repayment — building your future security or paying down what you owe.
The beauty of this rule is its flexibility. You don’t need complicated spreadsheets or financial jargon to follow it — just a rough sense of where your money is going each month. If your fixed costs are unusually high (say, you live in an expensive city), you can adjust the ratios slightly, but the principle stays the same: know your buckets, and don’t let one swallow the others.
2. Track Everything — With the Help of Technology
You don’t need a paper ledger or a complicated Excel file to know where your money goes. Today, there are dozens of expense-tracking apps that link directly to your bank account or let you log purchases in seconds. The real value isn’t the app itself — it’s the awareness it creates.
When you can see, in black and white, that you spent more on food delivery than on your monthly transportation, something clicks. That awareness alone is often enough to change behavior, even before you consciously decide to “budget better.” Tracking turns vague guilt about overspending into concrete, actionable information — and that’s the first step toward control.
3. Watch Out for “Lifestyle Creep”
One of the sneakiest financial traps is something called lifestyle creep. It happens when your income grows, but instead of saving the difference, your spending quietly grows right along with it. That coffee upgrades to a fancier café. The budget apartment becomes a bigger one. The old phone gets replaced a year early.
None of these choices feels irresponsible in the moment — that’s exactly why lifestyle creep is dangerous. It happens gradually and rationally, one small upgrade at a time. The fix is simple in theory, if not always in practice: when your income increases, keep your baseline lifestyle roughly the same, and direct the extra income straight into savings or investments. Future you will thank present you many times over.
4. Build an Emergency Fund — Starting Now
Life is unpredictable. A sudden medical bill, a broken laptop, or an unexpected job loss can derail even the most disciplined budget if you have no safety net. That’s why building an emergency fund should be one of your very first financial goals, not something you get around to “eventually.”
A solid target is three to six months’ worth of essential living expenses set aside in an easily accessible account. This fund isn’t for vacations or gadgets — it’s your financial airbag. Having it means you can handle a crisis without going into debt, and it also gives you the confidence to make bold career moves, like leaving a job that isn’t right for you, without panicking about how you’ll pay rent next month.
5. Saving Doesn’t Mean You Stop Investing in Yourself
It’s easy to think that being financially responsible means cutting every non-essential expense, including the ones that help you grow. But some spending is actually an investment, not a cost. Set aside a small amount each month for books, online courses, or professional certifications — for example, sharpening your skills in an in-demand area like digital marketing.
These investments often pay for themselves many times over by opening doors to promotions, raises, or entirely new career opportunities. The goal isn’t to save every dong you earn; it’s to spend intentionally, distinguishing between money that disappears and money that grows your future potential.
Final Thoughts
Managing your finances well isn’t about depriving yourself of every small joy today. It’s about buying something far more valuable: freedom and peace of mind for your future self. The habits you build now — however small they seem — compound over time, just like savings in a bank account.
So, which of these tips resonates with you the most? Or maybe you already have your own system for splitting up your monthly paycheck. Share your approach in the comments — you might just inspire someone else who’s navigating their first few paychecks, the same way I once was.
Leave a Reply