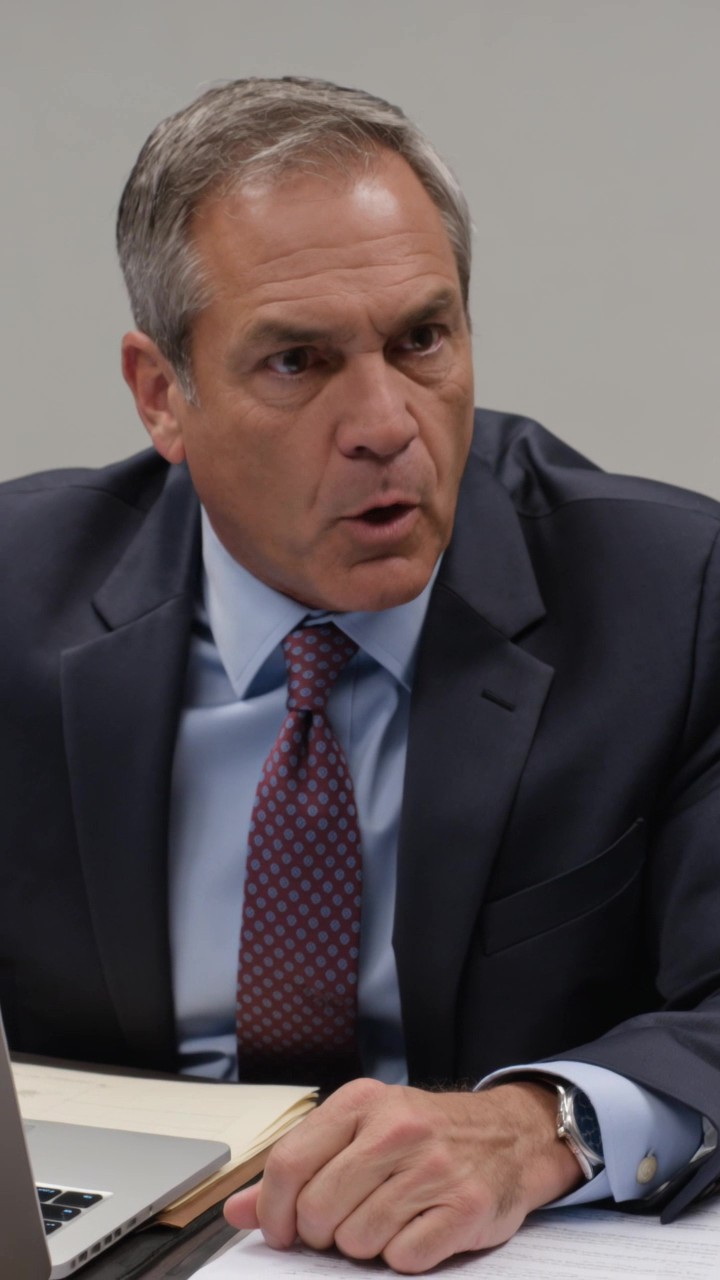
The three-million-dollar wire did not leave Harbor Community Credit Union.
That meant seventy-two Whitmore Construction employees still had payroll coverage, accrued leave, and retirement contributions protected inside the sale escrow.
It also meant Charles Whitmore’s personal retirement money remained intact.
The closing collapsed anyway.
The buyer withdrew before the fraud investigation could be completed.
Charles lost the deal he had spent eighteen months arranging.
Saving the money did not preserve the outcome he wanted.
It preserved the possibility of another one.
Nora Bell remained in the conference room while the credit union’s fraud team secured the laptop, security token, and printed wire instructions.
Charles looked at her as if eight years had folded into one table.
“You knew that account number.”
“Yes.”
“Why did you never give me this ledger?”
“I did.”
Nora pushed the old photocopy toward him.
His initials appeared on the upper corner.
Charles stared.
The memory returned slowly.
Eight years earlier, Whitmore Construction was expanding faster than its office systems could support.
Evan Whitmore, Charles’s oldest son, managed subcontractors and purchasing.
Nora handled payroll, invoices, and project accounts.
She noticed monthly payments to Harbor Bridge Logistics.
The company billed for equipment transport.
No site supervisor remembered seeing its trucks.
The mailing address belonged to a shared office suite.
The account code was HB-4417.
Nora placed the records before Charles.
Evan arrived with a different explanation.
He said Harbor Bridge was a confidential vendor used for short-notice equipment rentals.
Then he accused Nora of changing descriptions after payments cleared.
One vendor login had been used from Nora’s office computer.
That was enough for Charles.
He had raised Evan to inherit the company.
Nora was an employee who had worked there six years.
Charles chose blood before verification.
He suspended her access.
Within two days, Evan produced a spreadsheet suggesting Nora moved funds between cost codes to hide missing money.
The spreadsheet was false.
The underlying system had already been altered.
Nora requested an outside audit.
Charles refused.
He feared lenders would freeze expansion credit.
He fired her for “financial misconduct and breach of trust.”
No criminal charge followed because Charles did not want police examining the company.
The accusation spread informally through contractor networks.
Nora lost two job offers after references described her as unsafe around financial records.
She found work processing utility payments.
Then took night courses in banking compliance.
Starting again cost years.
Lower wages.
Lost confidence.
A marriage strained by financial pressure.
She eventually joined Harbor Community Credit Union as a fraud analyst.
The new title did not restore the reputation she lost.
It gave her tools to prevent similar harm.
Whitmore Construction continued operating.
The Harbor Bridge payments stopped after Nora left.
Charles interpreted that as proof he had removed the problem.
In reality, Evan closed the shell vendor because scrutiny had become dangerous.
He remained inside the company.
Years later, Charles decided to sell to Meridian Infrastructure Group.
The purchase agreement protected employee obligations through a separate escrow.
Harbor Community Credit Union was selected because the company’s main bank had a conflict with the buyer.
Nora disclosed her history immediately.
She asked to be removed from the assignment.
Her supervisor considered it.
Then decided her prior knowledge could be valuable if another analyst independently approved every action.
Nora agreed under written safeguards.
She would not control the funds alone.
She would review beneficiary ownership, payroll calculations, and fraud indicators.
The arrangement protected the transaction from both bias and retaliation.
The final wire instructions arrived late on closing day.
The escrow company name looked legitimate:
Harbor Bridge Settlement Services.
Different business registration.
Different website.
Same beneficiary account code:
HB-4417.
Nora stopped the transfer.
The fraud team discovered the settlement company’s identity documents belonged to a retired attorney who had never opened the account.
The buyer’s closing email had been compromised.
But the scheme also used internal information—exact payment timing, wire amount, employee escrow structure, and Charles’s private authorization phrase.
Someone inside Whitmore Construction had helped.
Evan denied involvement.
Then investigators found the fraudulent instructions had been printed from his assistant’s office and forwarded through an account linked to a device he used.
He eventually admitted giving transaction details to a former business associate who promised to “temporarily redirect” the money and return most of it after the closing dispute was settled.
Evan said he never intended to take employee payroll.
Nora answered during the formal interview:
“Money does not become less stolen because you planned to return part of it.”
Charles sat beside his attorney.
He looked older than Nora remembered.
“I believed him before.”
“Yes.”
“I believed him again.”
“Yes.”
He waited.
Nora did not relieve him of the pattern.
Charles had not committed the fraud.
He had repeatedly created the conditions where Evan’s explanations outranked other people’s evidence.
The company entered emergency restructuring.
The failed sale left bills due and confidence damaged.
Nora could have walked away after securing the funds.
Her credit-union role required her to remain only through the account freeze and reporting process.
Then she learned weekly payroll was due in four days.
The protected escrow could cover it, but releasing money required verified employee records.
Whitmore Construction’s payroll database contained irregular changes.
Workers risked delayed checks while the audit continued.
Charles asked Nora for help.
Not as a favor.
Through a formal contract between the company and credit union.
She could refuse.
Nora thought of the employees.
Equipment operators.
Office assistants.
Apprentices.
Drivers.
People who had not fired her.
People whose grocery money should not become punishment for Charles’s betrayal.
She agreed to verify payroll under three conditions:
An independent accountant joined the review.
Every hour was paid at her professional consulting rate.
And Charles signed a written statement correcting the accusation that had damaged her career.
Charles hesitated at the third condition.
His attorney warned that the statement could support Nora’s civil claim.
Nora closed the payroll file.
“Then hire someone else.”
Charles signed.
The correction was specific.
Nora had reported legitimate discrepancies.
No verified evidence showed she altered accounts or stole funds.
The company had terminated her without an independent audit.
References suggesting financial misconduct were withdrawn.
The statement went to every contractor, lender, and recruiter Charles could identify as having received the original accusation.
Nora did not demand language saying she had always been perfect.
She demanded the truth.
Payroll was released on time.
The company survived the first month.
Evan was removed from all operations and faced criminal proceedings.
The legal process continued beyond the sale crisis.
Charles appointed an interim management team that did not include family members.
Whitmore Construction was eventually sold to a regional employee-owned firm at a lower price than Meridian had offered.
Charles lost part of the retirement value he expected.
Workers kept their jobs, accrued benefits, and union agreements.
The ending was not financially perfect.
It was structurally safer.
Charles offered Nora the chief financial officer position before the final sale.
She declined.
“You need me because the person you trusted failed you.”
“I need you because you were right.”
“You knew I might be right eight years ago.”
Charles lowered his eyes.
“I was afraid of what the audit would find.”
“And I was easier to lose than your son.”
He did not deny it.
That honesty was late.
Still necessary.
Nora continued at the credit union.
Her corrected record opened opportunities that had been closed.
She received a promotion to senior fraud-prevention manager.
Her civil claim against Whitmore Construction ended in a settlement covering part of her lost income and legal expenses.
She accepted.
Saving Charles’s wire did not cancel his responsibility to repair what he could.
Months later, Charles requested a meeting without attorneys.
Nora agreed to twenty minutes at the credit-union café.
He brought the old HB-4417 ledger.
“I kept this.”
“You should give it to investigators.”
“They returned the copy.”
He touched his initials.
“This is the moment I chose not to know.”
Nora looked at him.
“It was one of them.”
Charles nodded.
He had expected a single dramatic mistake.
Nora understood harm often survives through repeated smaller choices.
Do not audit.
Do not ask again.
Trust the familiar person.
Describe the inconvenient worker as bitter.
He asked:
“Why did you stop the wire?”
Nora answered:
“Because the escrow held employees’ money.”
“And if it had been only mine?”
She considered the question.
“I hope I would still have stopped it.”
“That is not an answer.”
“It is the honest one.”
Nora did not need to prove moral perfection after betrayal.
She knew she acted because innocent workers were attached to the transaction.
Whether she would have saved Charles alone remained uncertain.
That uncertainty belonged to her.
At the credit union’s annual training, Nora used a redacted version of the case.
She showed analysts how emotional familiarity can defeat controls.
A parent trusting a child.
A manager trusting a longtime vendor.
A reviewer distrusting someone labeled difficult.
Then she displayed one code:
HB-4417.
“What saved the wire?” a trainee asked.
Nora answered:
“Not memory alone. Memory raised the question. Independent verification stopped the money.”
That became another lesson.
Personal history can alert people.
Systems must prove.
The company’s new owners established dual approval for vendors and protected internal reporting.
No family relationship could override a documented compliance hold.
Employees received annual statements showing exactly where payroll and retirement funds were held.
Charles retired.
He did not receive the public legacy he had imagined.
The company no longer carried his family name after the sale.
At the final office closure, he mailed Nora a blank ledger with one sentence inside:
For the records nobody should be punished for opening.
Nora kept the ledger.
She did not display it as forgiveness.
She used the first page for notes during a fraud review.
Practical.
Unsentimental.
The man who destroyed her career had needed her skill to prevent his company from being emptied.
She used that skill.
Not to restore him.
Not to return to his office.
To protect workers, expose the truth, and prove that rescue can reveal character without erasing accountability.
Leave a Reply